U.S. persons whose foreign financial accounts exceed $10,000 in total at any point during a calendar year must file an FBAR (FinCEN Form 114). The FBAR for calendar year 2025 was due April 15, 2026, with an automatic extension to October 15, 2026. The FBAR for calendar year 2026 is due April 15, 2027, with an automatic extension to October 15, 2027. Civil penalties reach $16,536 per non-willful violation and the greater of $165,353 or 50% of the account balance for willful violations. These 2025 inflation-adjusted amounts remain in effect for 2026. Filing is done electronically through the BSA E-Filing System, and records must be kept for five years.
Key Points:
- Who Needs to File: U.S. citizens, residents, and domestic entities with foreign accounts exceeding $10,000 in total value.
- Accounts Covered: Bank accounts, investment accounts, insurance policies with cash value, and more.
- Filing Process: Submit through the BSA E-Filing System; paper filing is rare and requires approval.
- Deadlines: April 15 following the calendar year reported, with an automatic extension to October 15. For calendar year 2026, that is April 15, 2027 and October 15, 2027.
- Penalties: Non-willful violations up to $16,536 per annual report; willful violations up to the greater of $165,353 or 50% of the account balance.
To avoid penalties, ensure timely filing, maintain detailed records, and consult a tax professional if needed.
What Changed for FBAR Filers in 2026
- No 2026 penalty inflation adjustment: OMB Memorandum M-26-11 (April 2026) cancelled the 2026 civil penalty adjustment because October 2025 CPI data was not published. The 2025 FBAR penalty maximums of $16,536 and $165,353 remain in effect.
- Signature authority relief extended again: FinCEN Notice FIN-2025-NTC3 extended the FBAR due date to April 15, 2027 for certain individuals who have signature authority over, but no financial interest in, foreign accounts.
- Calendar year 2025 deadlines have passed: The April 15, 2026 due date and the October 15, 2026 extended date are behind us. Anyone who missed them needs to file late as described below.
- Refreshed online form: Since September 28, 2025, the BSA E-Filing online FBAR form works on computers, tablets and phones.
Who Must File FBAR in 2026?
To figure out if you need to file an FBAR (Report of Foreign Bank and Financial Accounts), you’ll need to assess three main factors: your status as a U.S. person, the types of accounts you hold, and whether the total value of those accounts exceeds $10,000 at any point during the year. Let’s break down these criteria.
Definition of a U.S. Person
A U.S. person for FBAR purposes includes U.S. citizens, U.S. residents, and domestic entities such as corporations, partnerships, limited liability companies, trusts, and estates. Whether you’re an individual or represent a domestic entity, this definition applies.
You’re required to file if you have either a financial interest in or signature authority over one or more foreign financial accounts, and the total value of all those accounts exceeds $10,000 at any time during the year. Even if you don’t own the account, having the ability to control transactions, access funds, or make decisions on behalf of the account holder means you’re responsible for filing.
For example, corporate officers, trustees, or anyone with signing authority over foreign business accounts may need to file, even if they don’t personally own the funds.
Foreign Accounts Covered Under FBAR
FBAR rules apply to any foreign financial account located outside the U.S., regardless of the nationality of the financial institution. For instance, an account with a U.S. bank at a branch in Canada is considered a foreign account under FBAR rules. However, an account with a Canadian bank at a branch in the U.S. is not.

The types of accounts that fall under FBAR include:
- Bank accounts such as savings, checking, or certificates of deposit
- Investment accounts like brokerage or securities derivatives
- Commodity futures or options accounts
- Insurance or annuity policies with a cash value, such as whole life insurance
- Mutual funds or similar pooled funds
This means FBAR isn’t limited to traditional bank accounts – it covers a wide range of financial products.
The $10,000 Aggregate Threshold
If the combined value of all your foreign financial accounts exceeds $10,000 at any time during the year, you’re required to file an FBAR. Note that the $10,000 threshold applies to the total value of all accounts combined, not to each account individually.
To determine the maximum value of each account, use the highest balance recorded during the year in the local currency, convert it to U.S. dollars, and round up to the next whole dollar. For example, if an account’s maximum value is $15,265.25, you record it as $15,266. Use the Treasury Reporting Rates of Exchange published by the Bureau of the Fiscal Service for the last day of the calendar year. If no Treasury rate exists for a currency, use another verifiable rate and document the source.
Even if a single account temporarily exceeds $10,000 or if multiple accounts together cross this threshold, you’ll need to file. This is why reviewing all account statements for the year – not just the year-end balance – is so important. Since account balances can fluctuate throughout the year, keeping detailed records is essential for staying compliant.
FBAR Filing Deadlines and Extensions for 2026
Staying on top of FBAR deadlines is essential to avoid penalties and ensure compliance. Fortunately, the system provides an automatic extension, which simplifies the process and eliminates extra paperwork. Let’s break down the key dates and details you need to know.
Primary Filing Deadline
The FBAR is due April 15 of the year following the calendar year reported. The FBAR for calendar year 2025 was due April 15, 2026. The FBAR for calendar year 2026 is due April 15, 2027. This date matches the standard U.S. individual tax filing deadline, so you can handle both at the same time.
This April 15 deadline applies to all U.S. individuals who meet the FBAR filing criteria, regardless of their location.
Automatic Extension to October 15
FinCEN grants every filer an automatic six-month extension to October 15. For calendar year 2025 the extended date was October 15, 2026, and for calendar year 2026 it is October 15, 2027. This helps U.S. citizens living abroad who need extra time to gather details on their foreign accounts. Individuals covered by FinCEN Notice FIN-2025-NTC3 (signature authority only, no financial interest) have until April 15, 2027 to report calendar year 2025 signature authority.
Here’s what makes the automatic extension so convenient:
- No paperwork required: The extension applies automatically to all filers.
- Timely compliance: Filing by October 15 ensures your submission is considered on time.
- Available to everyone: All U.S. persons with FBAR obligations benefit from this extension.
An FBAR filed by October 15 is on time. You do not need to explain why you used the extension.
What if you miss both deadlines? File the late FBAR as soon as possible. The IRS advises filers who have not been contacted about a late FBAR, and who are not under civil examination or criminal investigation, to file late FBARs promptly to keep potential penalties to a minimum. Follow FinCEN’s instructions for filing late to explain your reason for the delay. Penalties for non-willful violations reach $16,536 per report, and penalties for willful violations reach $165,353 or 50% of the account balance, whichever is greater.
The automatic extension offers a safety net, making FBAR compliance less stressful, especially for those with complex international financial arrangements. Now that you know the deadlines, the next step is learning how to file your FBAR correctly.
How to File FBAR: Step-by-Step Process
Filing your FBAR is a fully online process, and getting familiar with the system and requirements beforehand can save you a lot of time and help you avoid mistakes. Everything is done through a government portal, so having all your account details ready before you start is key.
Filing Through the BSA E-Filing System
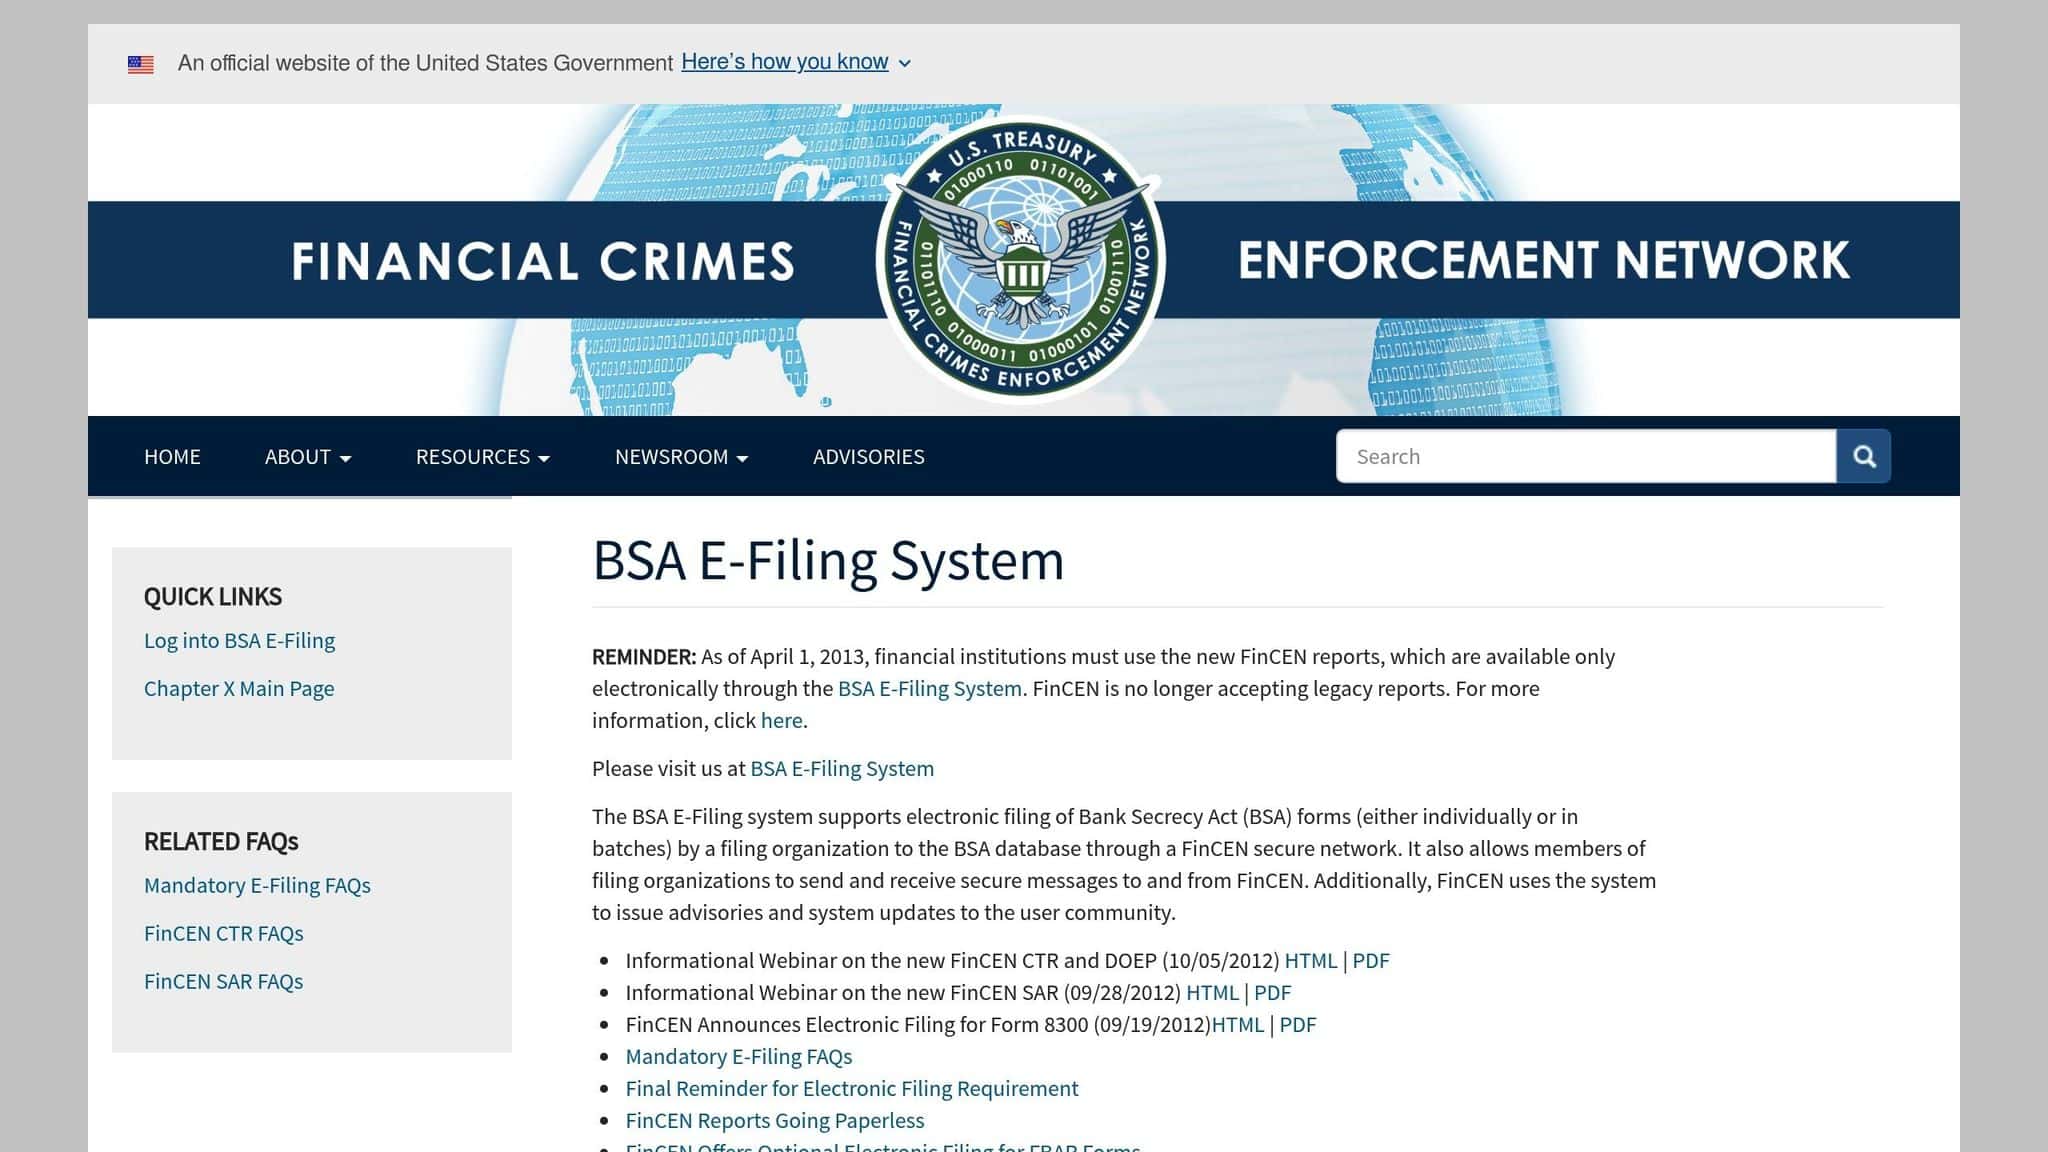
All FBARs must be filed electronically through the BSA E-Filing System, managed by the Financial Crimes Enforcement Network (FinCEN). Unlike your federal tax return, the FBAR is not submitted to the IRS and requires a completely separate filing.
If you’re filing as an individual, you can use a no-registration option for quick access. However, professionals who handle multiple filings will need to register for a User ID and password. This ensures the proper authorization is in place for handling client filings.
The system offers two filing options for individuals:
- File PDF FBAR: This option requires Adobe Reader and lets you save your work and return to it later. It’s a great choice if you need time to gather additional account details.
- File Online FBAR: This method doesn’t require Adobe Reader but must be completed in one session. It’s ideal if you already have all your account information ready and want to finish the filing in one go.
If electronic filing isn’t possible, you can contact FinCEN’s Resource Center to request an exemption. Paper filing is only allowed in rare cases and requires prior approval.
If someone else will be filing your FBAR for you, you’ll need to complete FinCEN Report 114a, Record of Authorization to Electronically File FBARs. This form ensures the third party has the legal authority to file on your behalf.
Once you’ve chosen your filing method, make sure you have all the necessary account information ready before starting.
Required Account Information
Before filing your FBAR, you’ll need detailed information for each account. Accuracy is critical, so double-check all the details you provide.
For each account, you’ll need to include:
- The account name (as it appears on bank documents)
- The account number (unformatted)
- The type of account
- The institution’s full name and address
- The maximum balance during the year (converted to U.S. dollars, rounded up)
For accounts in foreign currencies, you’ll need to use the Treasury Reporting Rates for the last day of the tax year. These official exchange rates are published specifically for tax reporting, ensuring consistency across all FBAR filings. Using other exchange rates could lead to compliance issues.
Once you’ve gathered all this information, the next step is to make sure you’re keeping proper records.
Recordkeeping Requirements
Filing the FBAR is only part of the process – you’re also required to maintain supporting documentation in case of future audits. You must keep these records for at least five years from the FBAR’s due date. This means holding onto documentation until five years after April 15th of the year following the calendar year being reported.
Here’s what to keep on file:
- Account name, number, and type
- Institution details
- Maximum balance
- Full bank statements for each foreign financial account
Additionally, retain a copy of your filed FBAR for your records. If you’re missing certain details when filing, use the best information available and document your efforts to obtain complete data. This shows that you’ve made a good-faith effort to comply.
For business accounts, recordkeeping rules may vary. If you’re an officer or employee filing an FBAR to report signature authority over a company’s foreign account, you don’t need to personally maintain the records – your employer is responsible for keeping them.
If you run into technical issues with the BSA E-Filing System, you can reach out to FinCEN’s BSA E-Filing Help Desk for assistance. They can help with system navigation and any filing-related questions.
sbb-itb-39d39a6
FBAR Penalties and How to Avoid Them
FBAR penalties range from monetary fines to criminal charges. Knowing the penalty structure and common pitfalls is crucial to staying compliant and avoiding costly mistakes that put your finances at risk.
Types of Penalties
The IRS categorizes FBAR violations into two main types, with penalties depending on whether the failure to file was accidental or deliberate.
Non-willful violations happen when someone fails to file due to negligence, an unintentional error or a good-faith mistake. The maximum penalty is $16,536 per violation, the inflation-adjusted figure set in January 2025 that remains in effect for 2026. In Bittner v. United States (2023), the U.S. Supreme Court held that the non-willful penalty applies per annual report, not per account. The IRS does not impose the non-willful penalty when the violation was due to reasonable cause.
Willful violations occur when someone knowingly fails to file or provides false information. The maximum penalty is the greater of $165,353 or 50% of the account balance at the time of the violation, and it applies for each year the FBAR was not filed.
In more severe cases, criminal penalties may apply. These include fines of up to $250,000 and up to five years in prison for tax evasion or false reporting. If the violation involves another U.S. law or is part of a pattern of illegal activity exceeding $100,000 within a 12-month period, penalties can climb to $500,000 and/or imprisonment for up to 10 years.
When determining willfulness, the IRS looks at factors such as repeated non-reporting, attempts to hide accounts, and the individual’s financial sophistication. These severe consequences highlight the importance of avoiding filing errors.
Common Filing Mistakes
Many FBAR violations stem from avoidable errors rather than deliberate misconduct. Awareness of these common mistakes can help you steer clear of penalties:
- Failure to File: Some individuals fail to file simply because they are unaware of the requirement.
- Misunderstanding the $10,000 Threshold: The $10,000 threshold applies to the combined value of all foreign accounts, not individual accounts. Even if each account is below $10,000, you must file if the total exceeds this amount at any point in the year.
- Incomplete Reporting: Once the aggregate threshold is met, you must report every foreign account, including accounts with balances under $10,000. This includes foreign life insurance policies with cash value, foreign retirement accounts and accounts held through beneficial ownership arrangements.
- Entity-Related Errors: U.S. LLCs, partnerships, disregarded entities, and estates have their own filing requirements. Majority business owners, trustees, grantors, and beneficiaries of trusts may also have individual obligations.
- Family Filing Errors: Each spouse files a separate FBAR unless all of the non-filing spouse’s foreign accounts are jointly owned with the filing spouse, the filing spouse reports them on a timely FBAR, and both spouses sign FinCEN Form 114a. A minor with foreign accounts above the threshold has a filing obligation, and a parent or guardian files on the child’s behalf.
- Record-Keeping Failures: Not keeping adequate records, like bank statements, can lead to non-compliance with Bank Secrecy Act record retention rules .
- Signature Authority Confusion: Individuals with signature authority over foreign business accounts must file even if they do not own the accounts, and this obligation is commonly overlooked.
Best Practices for Compliance
To avoid both accidental and intentional violations, follow these best practices. Staying compliant requires methodical recordkeeping and proactive filing habits:
- Keep Detailed Records: Review all account statements to determine the highest balance during the year. Convert the maximum value into USD using the Treasury’s Financial Management Service rate for December 31 of the reporting year. Document your conversion method and retain these records for at least five years.
- File Early and Verify Accuracy: Filing promptly shows good-faith compliance. Double-check account numbers, maximum balances, currency conversions, and institution details for accuracy before submitting your FBAR.
- Address Missed Filings Quickly: If you missed filing in previous years, submit the late FBARs before the IRS contacts you and explain the reason for the delay. If you also have unreported income from non-willful conduct, the IRS Streamlined Filing Compliance Procedures provide a structured path back into compliance.
- Consult a Professional: For more complex situations, work with a tax professional who specializes in international compliance to ensure all obligations are met .
- Err on the Side of Caution: If you’re unsure whether an account or entity needs to be reported, it’s safer to file. If exact account values are hard to obtain, use conservative estimates.
- Retain Documentation: Keep records of any circumstances affecting timely filing. Save the confirmation page with your BSA Identifier number and keep bank statements for all foreign accounts for at least five years from the FBAR due date.
FBAR Filing Requirements 2026: Summary
If you’re a U.S. person with foreign financial accounts, understanding FBAR filing requirements is a must. An FBAR must be filed if the total balance across your foreign accounts exceeds $10,000 at any point during the calendar year.
To comply, file FinCEN Form 114 through the BSA E-Filing System by April 15 of the year after the calendar year reported, with an automatic extension to October 15. For calendar year 2026, the dates are April 15, 2027 and October 15, 2027. Missing these deadlines leads to serious consequences.
Non-compliance carries steep penalties. Non-willful violations reach $16,536 per annual report. Willful violations reach the greater of $165,353 or 50% of the account balance. Criminal penalties include fines of up to $250,000 and up to five years in prison, rising to $500,000 and up to 10 years when the violation is part of a pattern of illegal activity. These civil amounts were set in January 2025 and were not adjusted for 2026.
Missed the deadline? File late FBARs as soon as possible if the IRS hasn’t reached out to you yet. You may also qualify for the IRS Streamlined Compliance Procedures, which allow penalty-free catch-up filings under certain conditions.
To stay compliant, keep thorough records for five years from the FBAR due date, file electronically via the BSA E-Filing System, and consult a professional for complicated situations. The IRS has made FBAR compliance a focus area, so timely and accurate filing is more important than ever.
For entrepreneurs and investors operating globally, strict FBAR compliance isn’t just about avoiding penalties – it’s essential for protecting assets and optimizing taxes. Global Wealth Protection offers expert advice to help you navigate these complex international reporting rules.
FAQs
What happens if I miss the FBAR filing deadline in 2026?
Missing the FBAR deadline exposes you to civil penalties. A non-willful violation carries a penalty of up to $16,536 per annual report. A willful violation carries a penalty of up to $165,353 or 50% of the account balance, whichever is greater. The key factor is whether the failure to file was intentional.
If you missed the deadline and the IRS has not contacted you, file the late FBARs as soon as possible with a statement explaining why they are late. If you also have unreported income from the accounts and your conduct was non-willful, the IRS Streamlined Filing Compliance Procedures offer reduced or no penalties. The statute of limitations for assessing FBAR civil penalties is six years from the date of the violation, so act quickly.
How can I tell if I have signature authority over a foreign account for FBAR filing?
If you have signature authority over a foreign account, it means you can control the movement of funds or direct transactions linked to that account, even if it isn’t registered under your name. This could involve signing documents or issuing instructions that affect the account’s finances.
If this applies to you, federal regulations require you to file an FBAR to report the account. Make sure to carefully review the specific rules to determine your filing responsibilities.
What records should I keep to comply with FBAR requirements?
To comply with FBAR recordkeeping requirements, it’s important to maintain thorough documentation for your foreign financial accounts. This includes bank statements, account numbers, and the dates when accounts were opened or closed. Keep these records for at least five years from the FBAR filing deadline, as mandated by law.
Staying organized with your records not only helps you meet legal obligations but also ensures you’re ready to address any audits or inquiries. Securely storing these details is a smart way to stay prepared.